Before you send anything
Look at the report first.
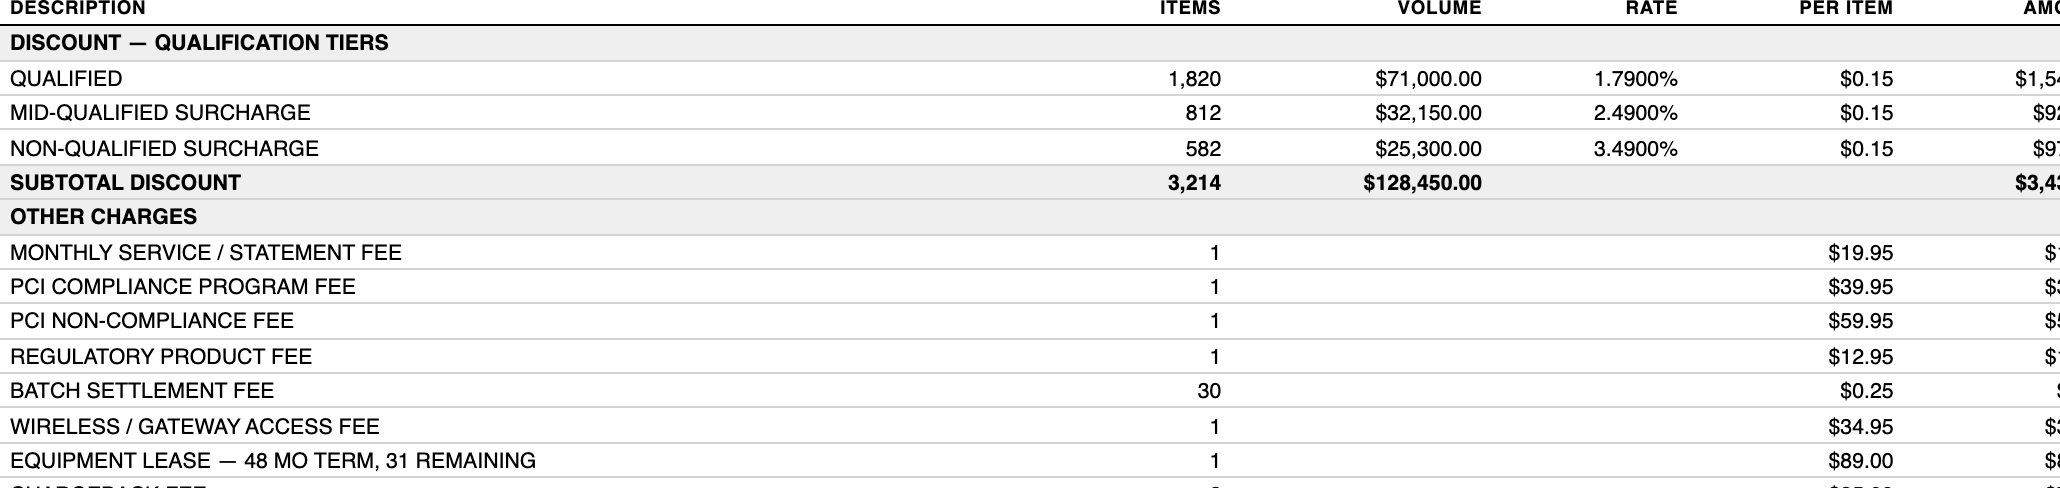
This is what lands in your inbox. Read it, then decide whether you want me anywhere near your statement.
Merchant statement audit
Prepared for Sample Merchant LLC
Prepared by Troy Walker, CEO, JOOLT
The same lines, priced. This is the section owners read first:
Every figure above is an example. This is the layout of the report, not a client result and not a prediction about your business. Your report carries your own lines and your own numbers.
The full report has eight sections: Executive Summary, Pricing Model, Junk Fees and Removable Charges, Assessment and Passthrough Overcharges, Non-Qualified Downgrade Analysis, Terminal Lease flags, Recommended Actions, and Next Steps.
There is a name and a title on it. Troy Walker, CEO of JOOLT. If something in your report is wrong you know exactly who to email about it.
Before you send me anything
Do this yourself. It takes twenty seconds.
Find two numbers on your statement: total fees charged and total card volume. Divide the first by the second.
That is your effective rate. It is the only number that matters, and your statement is arranged so that you never see it.
Under 2.6%
You are probably priced fine. Send it anyway if you want it confirmed in writing. I will tell you so, and that is a real answer, not a soft no.
Over 2.6%
Something on that statement is worth reading. It may be one line. It is rarely nothing.
Over 3%
It is not close. At that rate the question is not whether there is something, but how much.
Your processor's rep earns residuals on what you pay. That is the whole reason nobody has shown you this arithmetic before.
How this actually goes
Knowing you are overpaying is not the same as fixing it.
That is why this money sits there for years after an owner finds out. Calling a processor's retention line ranks below hiring a dishwasher, and it should. So I do that part.
- Send one statement. 30 seconds, from your phone.
Then, later, one decision. When the report comes back you say whether you want it fixed. If you say no, that is the end of it and you owe nothing.
- Read every line of your statement and price it against what it should be.
- Send you the number in writing within 24 hours. Free, whatever it says.
- Do the calling, the hold music and the rounds of counter-offers.
- Read your next 2 statements and prove the money actually came off.
I read your contract before anything moves, and nothing switches without your sign-off.
You do not talk to your processor. You do not fill out forms. You do not comparison-shop.
The offer, in plain words
I audit your merchant statement for free. If I find real savings, I'll execute the recovery on your behalf. You don't talk to your processor, you don't fill out forms, you don't comparison-shop.
You pay me a percentage of what I actually save you, only after we see the reduced fees on your next statement. If I can't recover at least $3,000 a year, you pay nothing.
What that percentage is depends on what I find, and we settle it on a call after you have read your report. Nothing is charged before then, and nothing is charged at all until the lower fees show up on a statement you are holding.
Free. 24 hours. One file.
Send it
Two questions, then your statement.
What happens to the file you send
- It goes straight into private storage. It is used for exactly one thing: producing your report.
- It is never sold, never published, and never shown to a processor. Nobody buys a lead list with your name on it, and no rep calls you because you filled this in.
- Black out anything you like before you send it. I do not need your bank account number or your full merchant number. The fee lines are what matter.
- Ask me to delete it and I delete it. One email to admin@thejooltgroup.com and it is gone.
- Back within 24 hours. One statement, one written report, whatever it says. If your statement is already priced well, the report tells you that and we are done.